Most CEOs think about audits and reviews as something you do for a transaction — a box to check once a buyer or investor is already at the table. By then, it’s usually too late to get the full value out of the exercise.
The businesses that command the smoothest diligence processes — and the best valuations — are the ones that treat assurance work as a standing discipline, not a pre-sale scramble. Here’s why that distinction matters, and what it actually looks like in practice.
When a buyer’s diligence team opens your data room, the clock is already running. Every week spent reconstructing prior-year reconciliations, tracking down missing support, or explaining unusual account activity is a week of lost momentum — and lost leverage. Deals don’t die because the numbers are bad; they die (or get repriced) because the numbers can’t be explained quickly and credibly.
A business with audit-ready financials walks into that process with:
- Clean, reconciled trial balances going back multiple years
- Documented accounting policies and consistent application of them
- Supportable revenue recognition, especially for businesses with complex contracts or multiple revenue streams
- A clear paper trail on related-party transactions, one-time items, and add-backs
None of that happens in the 90 days before a Letter of Intent. It happens because the business has been operating under assurance-level discipline all along.
Faster diligence, fewer surprises.
Buyers price in risk. When financials require extensive normalization, restatement, or explanation, that uncertainty shows up as a lower multiple, additional escrow, or reps-and-warranties friction. Clean, assurance-tested financials remove a major source of that discount.
Credibility on the add-backs.
Every seller wants EBITDA add-backs recognized. Buyers are naturally skeptical of add-backs that show up for the first time in a Quality of Earnings report. When those adjustments are already visible and consistently treated in financials that have been reviewed or audited over time, they’re far easier to defend.
Negotiating leverage.
A CEO who can hand over three years of clean, assurance-level financials on day one of diligence is negotiating from a position of strength. A CEO who needs six weeks to produce them is not.
Reduced deal risk on both sides.
This isn’t just about getting a better price — it’s about the deal actually closing on the terms both parties expected. Financial surprises during diligence are one of the most common reasons deals get repriced or terminated.
The most common mistake isn’t neglecting the financials — it’s waiting for a specific trigger event (a term sheet, a banker’s engagement, an active buyer conversation) before investing in the underlying financial infrastructure. By that point, you’re paying rush rates for cleanup work under deal pressure, and every finding your accountants uncover becomes a live issue in an active negotiation instead of something already resolved.
The second mistake is treating a compilation or informal bookkeeping close as equivalent to assurance-level work. They’re not. A review or audit brings a level of independent testing, documentation, and consistency that a compilation simply doesn’t — and buyers’ diligence teams know the difference immediately.
Getting to M&A-ready financials isn’t about a single engagement — it’s about establishing the habits an audit or review process forces on an organization, well before a transaction is on the horizon:
- Closing the books on a consistent monthly or quarterly cadence with reconciled balance sheet accounts
- Documenting accounting policies for revenue recognition, inventory, capitalization, and other judgment areas
- Maintaining clean support for related-party transactions and owner-driven expenses
- Engaging in periodic reviews or audits — even before they’re required by a lender or investor — so that any issues surface and get resolved on your timeline, not a buyer’s
For CEOs who are even considering a sale, a recapitalization, or bringing in outside capital in the next few years, the right time to start this work is now — not when the first call from an interested buyer comes in.
Assurance work isn’t just a compliance requirement or a pre-deal formality. For a CEO thinking about the eventual sale or capitalization of their business, it’s one of the highest-leverage investments available — because it turns the most stressful, highest-stakes phase of a transaction into the most straightforward one.
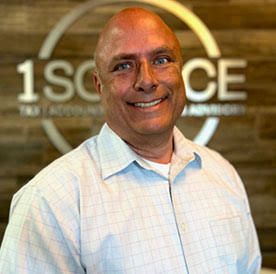
Paul Hays is the Assurance Practice Leader at 1Source, overseeing all assurance services with over 34 years of public accounting experience. Recognized for his business acumen and financial expertise, Paul excels in driving organizational growth, managing cross-functional initiatives, and communicating effectively with corporate governance stakeholders. He specializes in analyzing operations, providing actionable recommendations to improve strategies and performance, and aligning operational decisions with financial goals.
Paul Hays, Assurance Practice Leader, 1Source
This article is for general informational purposes and does not constitute audit, tax, or transaction advisory advice. Businesses considering a sale, recapitalization, or capital raise should consult with their accounting and legal advisors to assess their specific readiness.